

Buying a car through a loan may make ownership easier, but poorly structured financing can quietly create long-term financial pressure.
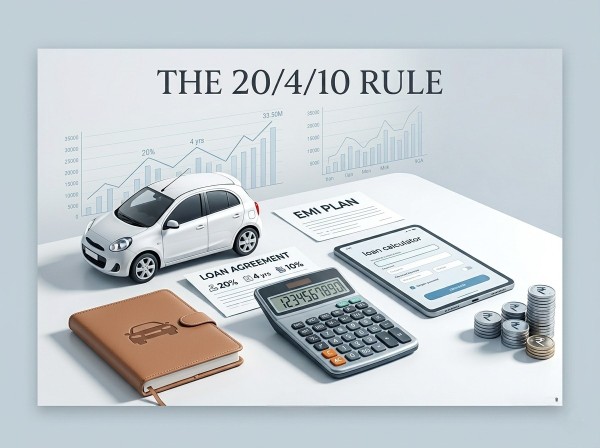
The 20/4/10 rule is a widely followed budgeting framework designed to help buyers keep car ownership financially manageable without overstretching household income.
The rule is built around three simple principles:
- pay at least 20% as down payment
- limit the car loan tenure to 4 years
- keep total monthly car expenses within 10% of monthly income
The framework aims to reduce excessive debt, control interest costs and prevent buyers from locking themselves into stressful EMIs over long periods.
What the 20/4/10 Rule Means
The formula divides car affordability into three key financial checkpoints.
20% Down Payment
Buyers should ideally pay at least 20% of the car’s on-road price upfront.
A higher down payment helps:
- reduce overall loan burden
- lower monthly EMIs
- cut total interest payable
- reduce financial stress over time
Smaller down payments may appear attractive initially but usually increase long-term repayment pressure.
4-Year Loan Tenure
The remaining loan amount should ideally be repaid within four years.
Long-duration car loans may reduce EMI size temporarily, but they also:
- increase total interest cost
- extend debt obligations unnecessarily
- keep buyers tied to a depreciating asset for longer periods
The four-year structure is generally considered a balance between affordability and responsible debt repayment.
10% Monthly Expense Limit
Total monthly vehicle-related expenses should remain within 10% of monthly income.
This includes:
- loan EMI
- fuel expenses
- insurance premiums
- servicing and maintenance costs
The objective is to ensure car ownership does not interfere with savings, investments or emergency preparedness.
Illustrative Affordability Breakdown
| Car Price | Minimum Down Payment | Approx Loan Amount | Suggested Monthly Income* |
| ₹5 lakh | ₹1 lakh | ₹4 lakh | Around ₹50,000 |
| ₹10 lakh | ₹2 lakh | ₹8 lakh | Around ₹1 lakh |
| ₹15 lakh | ₹3 lakh | ₹12 lakh | Around ₹1.5 lakh |
*Assumes total monthly vehicle expenses remain within 10% of income.
Why This Rule Matters
Many buyers evaluate affordability based only on EMI size while ignoring total ownership costs.
This often results in situations where:
- long-tenure loans appear cheaper initially
- maintenance and insurance costs become difficult later
- emergency savings get compromised
- monthly budgets become heavily dependent on fixed EMIs
The 20/4/10 framework works as a financial discipline tool by aligning vehicle purchases with actual income capacity rather than aspirational spending.
How the Rule Helps Protect Financial Stability
Following the framework can help buyers avoid several common borrowing mistakes, including:
- taking excessively long car loans
- spending too much monthly income on EMIs
- underestimating ownership expenses
- weakening emergency savings
- falling into long-term debt dependency
The rule also encourages buyers to choose vehicles that fit their financial profile instead of stretching budgets unnecessarily.
Why This Matters for Individuals and Families
For salaried professionals and middle-income households, vehicle loans are often among the largest recurring financial commitments after housing costs.
Poorly structured car loans can affect:
- monthly cash flow stability
- long-term savings goals
- investment capacity
- emergency preparedness
The risk becomes higher when low down payments are combined with long repayment periods and rising lifestyle expenses.
What Financial Advisors and Wealth Professionals Should Watch
For financial planners, wealth advisors and tax professionals, rising vehicle financing trends highlight the need for broader household cash flow assessment before large discretionary purchases.
Advisory conversations increasingly involve:
- debt-to-income analysis
- EMI sustainability assessment
- emergency fund adequacy
- long-term savings impact
- asset depreciation awareness
The focus is gradually shifting from loan eligibility towards long-term financial sustainability.
Closing Perspective
The 20/4/10 rule is not a law or regulation for any kind of borrowing.
Rather, it acts as an economic guideline for borrowers that will help them prevent over-borrowing while ensuring financial flexibility in the future.
In most instances, the true cost of owning a car involves the total effect of its EMI payments, insurance, and maintenance charges over several years.
For individuals planning to purchase a new vehicle, the tool provides a structured approach to assessing whether the car is affordable within their budget constraints.