

The discussion around whether a ₹15 lakh Cost to Company (CTC) can result in significantly lower tax liability under the new tax regime has gained attention in recent months.
In practice, the outcome depends less on headline salary and more on how compensation is structured within the limits permitted under tax rules and employer policies.
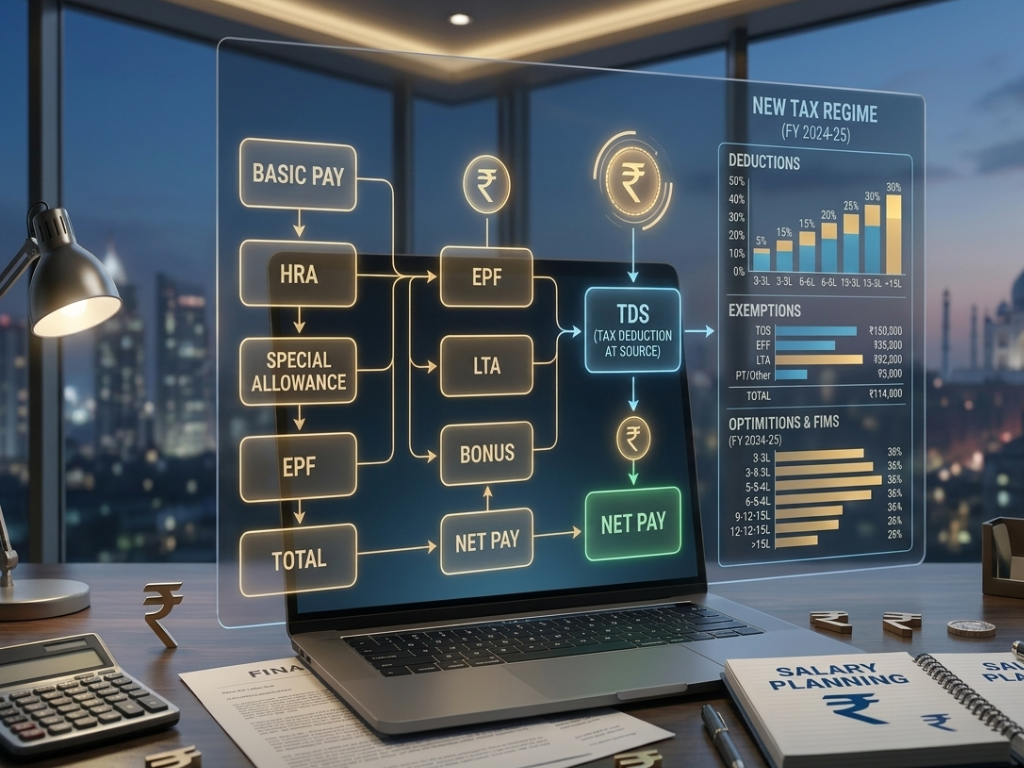
The new regime continues to tax salary income through slab-based rates. What changes is the extent to which certain reimbursements and employer-provided benefits form part of taxable salary.
Why salary structure matters more now
Under the new tax regime, many traditional deductions available under the old regime are no longer applicable.
As a result, compensation design has become increasingly important in determining post-tax take-home income.
Two employees with the same ₹15 lakh CTC may still see differences in taxable income depending on:
- salary composition
- reimbursement policies
- treatment of official-use expenses
- employer benefit structures
The total compensation may remain unchanged, but the taxable portion can vary within permissible limits.
Where tax efficiency may arise
The benefit does not come from avoiding tax altogether. It comes from correct classification of eligible components under applicable tax rules.
Certain reimbursements linked directly to official work may remain outside taxable salary when supported by appropriate documentation and employer policy.
These may include:
- mobile and internet reimbursements used for official purposes
- employer-provided laptops or devices meant for work usage
- structured meal benefits within prescribed limits
- certain health and wellness benefits provided uniformly under company policy
In some cases, official-use travel or vehicle reimbursements may also receive favourable tax treatment where documentation and usage conditions are properly maintained.
The treatment depends heavily on factual usage, payroll structure and supporting records.
Why this matters for employees
For salaried individuals, the difference is often visible in monthly take-home income rather than headline CTC.
Employees increasingly evaluate:
- post-tax income
- reimbursement flexibility
- benefit structures
- payroll design
rather than salary figures alone.
However, these benefits are not automatic. They depend on:
- actual expense usage
- employer frameworks
- documentation standards
- compliance with tax rules
Without proper support, reimbursements may become taxable during assessment or review.
Why this matters for employers
For employers, salary structuring has evolved beyond payroll administration into a compensation planning tool.
Flexible benefit structures allow organisations to improve employee tax efficiency without necessarily increasing overall compensation cost.
At the same time, this places greater importance on:
- payroll compliance
- documentation controls
- consistency in reimbursement policies
- correct tax treatment across employee categories
Improper structuring or weak documentation can create future compliance exposure.
A shift in compensation planning
The broader shift under the new tax regime is from deduction-driven tax planning to structure-driven tax efficiency.
Earlier, employees focused heavily on claiming deductions after income was earned. Increasingly, optimisation now happens at the salary design stage itself.
This has made payroll structure, HR policy and compliance processes more relevant in determining effective post-tax income.
Important practical limitation
A ₹15 lakh CTC does not automatically translate into zero tax liability under the new regime.
Any claim of extremely low or nil tax depends on:
- the actual composition of salary
- nature of reimbursements
- employer policy framework
- documentation quality
- eligibility under tax rules
In practice, tax efficiency is possible within defined limits, but broad claims around “zero tax salary” should be viewed cautiously.
Closing perspective
The new tax regime has changed how salaried individuals approach compensation planning.
The focus is no longer only on deductions, but on how salary itself is structured and documented. For both employers and employees, this makes compensation design an increasingly important part of financial planning and payroll compliance.
Ultimately, the effectiveness of any structure depends less on aggressive tax positioning and more on whether the arrangement can withstand scrutiny under applicable tax rules.

