

For many families, the process of claiming shares and securities after the death of an investor has long been one of the most overlooked and underestimated legal challenges in personal finance. Piles of documents, multiple affidavits, legal certificates and weeks of waiting have been the norm.
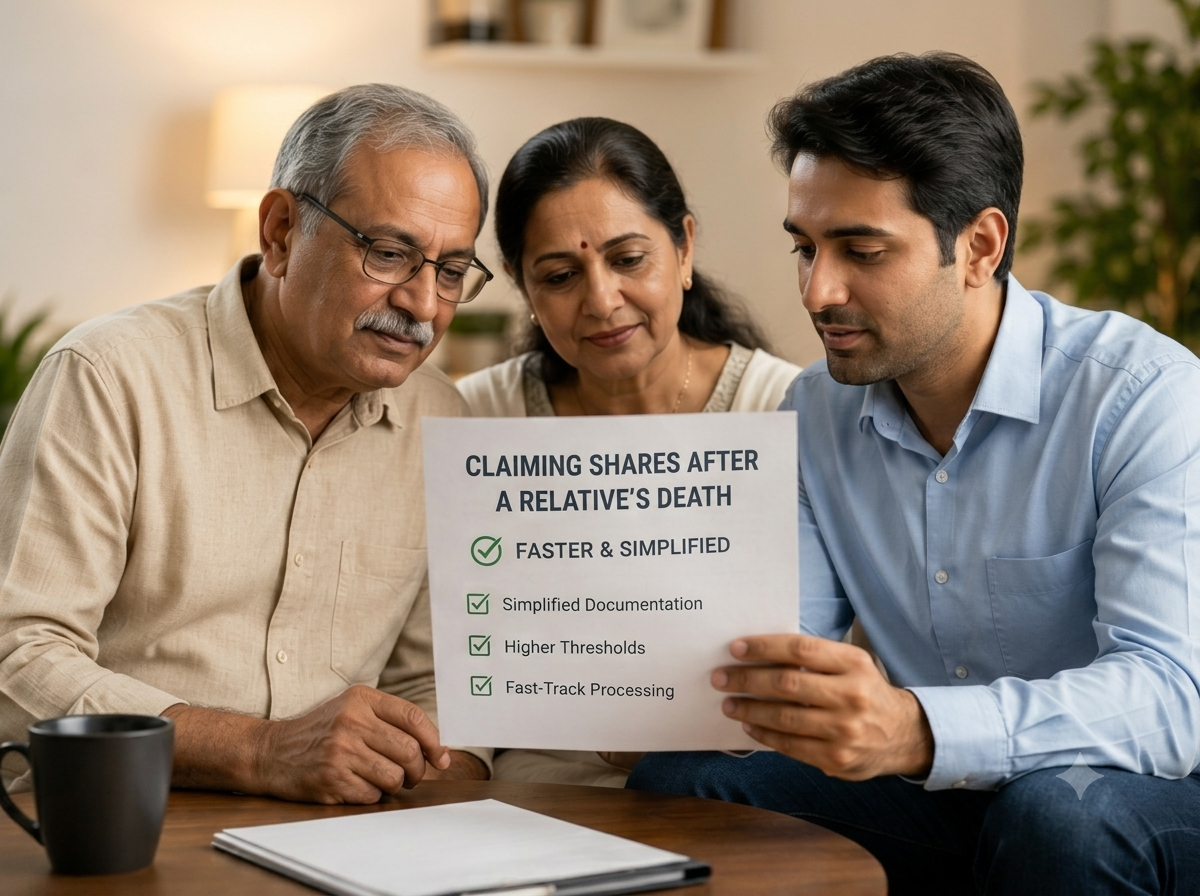
The Securities and Exchange Board of India has now approved a series of reforms aimed at changing exactly that. The new framework introduces simplified documentation, higher claim thresholds and a fast-track mechanism for smaller holdings, making the transmission process significantly more accessible for nominees and legal heirs.
Why Families Have Struggled With This Process for So Long
Claiming inherited securities has traditionally required families to gather multiple affidavits, no-objection certificates and, in many cases, a probate of the deceased’s will before any transfer could take place. This came at a time when families were already dealing with grief, making the procedural burden feel especially heavy.
SEBI’s reforms acknowledge this reality. The changes are designed to reduce paperwork, speed up processing and bring more investors within the scope of simplified procedures, without compromising the integrity of the verification process.
The New Fast-Track Route and Revised Thresholds for Simplified Claims
One of the most meaningful changes is the introduction of Quick Transmission Processing for small-value claims, alongside a revision of the limits under which simplified documentation applies.
| Holding Type | Earlier Limit | Revised Limit |
| Physical holdings per listed company | Rs 5 lakh | Rs 10 lakh |
| Demat holdings per beneficial owner | Rs 15 lakh | Rs 30 lakh |
Claims falling within the revised limits can now be processed through the simplified mechanism with minimal documentation. The higher thresholds are expected to bring a significantly larger number of families within the scope of faster transmission.
What Has Changed in Terms of Documentation
Several specific documentation requirements have been revised or removed entirely.
Key changes include:
- PAN details no longer need to be submitted separately, as they are already available in demat account records
- the mandatory probate requirement for wills has been eliminated, in line with recent changes in succession law
- a combined affidavit-cum-No Objection Certificate can now be submitted instead of separate documents
- QR code-enabled death certificates will be accepted for easier verification
- for deaths occurring outside India, verification can now be completed through overseas branches of Indian banks or foreign banks with correspondent banking relationships with Indian banks
Together, these changes are expected to significantly reduce the volume of documents that families need to gather during what is already a difficult period.
When Will These Rules Come Into Effect
SEBI has approved the reforms but has not yet announced an implementation date.
A detailed circular outlining the operational framework and effective timeline is expected in the coming weeks. The proposals were developed after consultations with registrars, share transfer agents and the Association of Mutual Funds in India. Investors and their families should watch for the formal circular before acting on any transmission-related matters under the new framework.
What This Means for Investors and Succession Planning
The reforms carry a broader message for investors who hold shares and other securities. Keeping nominee details updated is no longer just good practice — it is now supported by a faster and more accessible transmission framework. For those with significant holdings, the changes reduce the risk of inherited investments being tied up in prolonged administrative procedures. For families dealing with smaller claims, the Quick Transmission Processing route offers a genuinely simplified path to accessing what is rightfully theirs.
Closing Perspective
SEBI’s transmission reforms address a gap that has affected families across income levels for years. The changes are practical, targeted and long overdue.
Once the implementation circular is released, nominees, legal heirs and investors should review their existing nominations and ensure their records are in order. The new framework will only deliver its full benefit to those who have kept their investment documentation up to date.