

With the tax audit deadline approaching, many professionals and business owners have raised concerns about a new ₹75,000 late fee for delays in filing the Tax Audit Report. This has caused understandable concern across the taxpayers, so let us set the record straight.
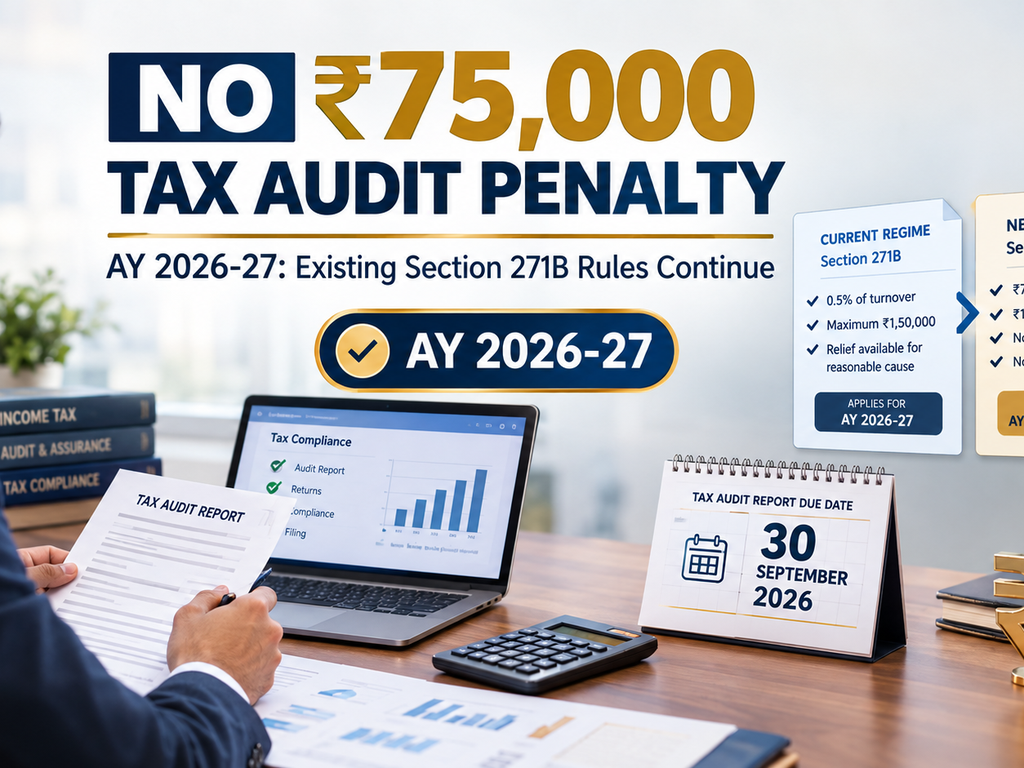
The ₹75,000 fee does not apply for AY 2026-27.
What Does the New Provision Under Section 428(c) Say?
The Income Tax Act, 2025 introduces a new penalty structure under Section 428(c), and it is considerably stricter than the framework taxpayers are currently used to:
- Delay up to 1 month in filing the Tax Audit Report under section 63 attracts a fee of ₹75,000
- Delay beyond 1 month raises this fee to ₹1,50,000
Even a delay of a single day would place a taxpayer in the ₹75,000 slab once this provision takes effect. This fee is fixed and mandatory, with no scope for discretion.
This marks a significant departure from the existing law. Under section 271B, the penalty is 0.5% of turnover, subject to a maximum of ₹1,50,000, and it is discretionary in nature. Where reasonable cause is proved under section 273B, no penalty is levied at all.
Why the New Fee Does Not Apply Right Now
As per Budget 2026 and the Finance Bill 2026, this new fee structure comes into effect from 1st April 2026 and applies from Tax Year 2026-27 onwards, which in terms of assessment year means AY 2027-28 onwards.
There is no change to the applicability of section 271B for the current tax audit cycle.
Position for AY 2026-27
For the current assessment year, the following continues to apply:
- The due date for the Tax Audit Report is 30th September 2026 for regular tax audit cases
- Section 271B continues to govern the penalty, at 0.5% of turnover, capped at ₹1,50,000, with relief available where reasonable cause is shown
- There is no ₹75,000 fixed fee for a one-day delay under the rules currently in force
Conclusion
There is no cause for concern this tax audit season. The ₹75,000 fee under section 428 is real and is on its way, but it applies from Tax Year 2026-27, which is Assessment Year 2027-28, and not the current cycle. For AY 2026-27, taxpayers and professionals continue to be governed by the existing section 271B framework, with the penalty capped at ₹1,50,000, calculated at 0.5% of turnover, and relief available on proof of reasonable cause.
That said, this year should be treated as a preparation window rather than business as usual. Once the new fee regime comes into force, the reasonable cause relief under section 273B, which currently applies to section 271B, will not extend to the new section 428(c) fee. So while the 30th September 2026 deadline can still be approached under the existing, more accommodating rules, this is a sensible time to begin tightening internal audit processes and filing timelines ahead of the stricter regime that lies ahead.