

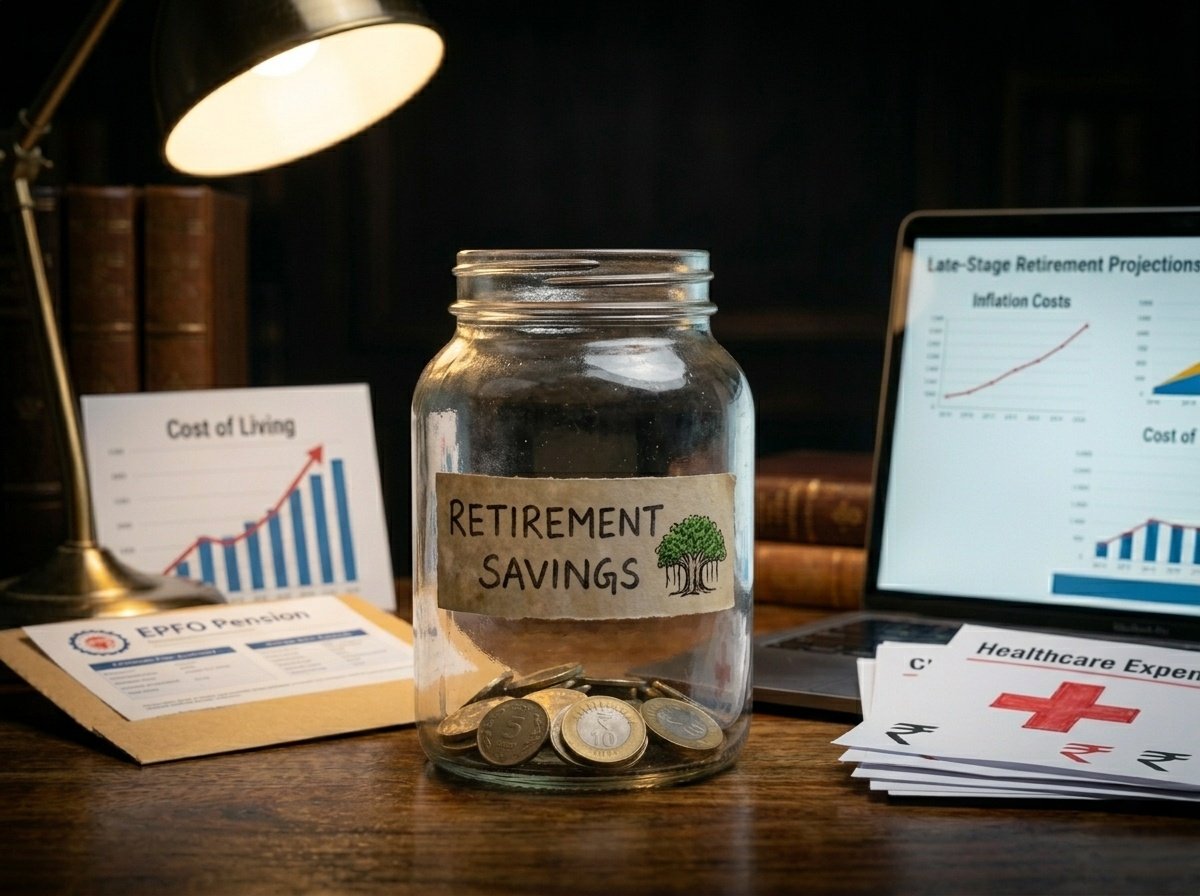
A recent retirement planning survey conducted among Indians in the 40–60 age group highlights a growing disconnect between retirement confidence and actual financial preparedness.
While a majority of respondents said they expect to retire comfortably, most admitted they do not have a structured retirement plan in place.
The findings reflect a broader issue in Indian financial behaviour:
Retirement planning often starts late, relies heavily on informal advice and underestimates the long-term impact of inflation and healthcare costs.
Confidence remains high despite weak planning
One of the more striking findings from the survey is the gap between perception and preparation.
A large percentage of respondents said they do not have a detailed retirement plan, yet many still remain confident about their financial future after retirement.
The issue becomes more significant when viewed alongside another trend:
most respondents had never consulted a professional financial adviser for retirement planning.
Instead, many continue relying on:
- family recommendations
- informal financial guidance
- traditional savings behaviour
rather than structured long-term planning.
This creates a situation where financial confidence is often not backed by realistic retirement modelling.
Healthcare costs are becoming a major blind spot
The survey also highlights how retirement planning frequently underestimates medical expenses.
Many respondents expected expenses to decline after retirement. In reality, healthcare inflation in India has historically remained significantly higher than general inflation.
Over long retirement periods, this difference compounds sharply.
For retirees, healthcare costs often become one of the largest recurring financial pressures because:
- medical needs typically increase with age
- insurance coverage may become more limited or expensive
- fixed retirement income may not rise at the same pace as healthcare costs
This becomes especially relevant as life expectancy continues improving and retirement periods extend across two decades or more.
The retirement savings gap remains substantial
The survey points to a significant gap between current retirement savings and expected retirement needs.
Many respondents reported retirement savings that were materially lower than their target retirement corpus.
The issue is partly structural.
A large number of individuals begin retirement planning relatively late in their careers, leaving a shorter compounding window before retirement age.
Even where regular savings exist, delayed investing reduces the long-term impact of compounding and increases dependence on higher future contributions.
For higher-income groups, the gap often persists despite larger savings because lifestyle expectations and future financial obligations also rise substantially.
Traditional retirement assets still dominate
The findings also show continued preference for traditional retirement assets such as:
- fixed deposits
- mutual funds
- real estate
- gold
Meanwhile, adoption of retirement-focused products such as the National Pension System (NPS) remains comparatively limited.
This reflects a broader behavioural trend in India where retirement planning is still often linked to familiar savings instruments rather than fully diversified long-term retirement strategies.
Why delayed retirement planning becomes risky
The financial impact of delaying retirement planning is usually underestimated in the early earning years.
Late planning affects:
- compounding potential
- retirement corpus growth
- ability to absorb inflation
- long-term healthcare preparedness
At the same time, future uncertainty around:
- healthcare expenses
- employment continuity
- lifestyle inflation
- longevity
makes retirement modelling increasingly important.
The longer planning is postponed, the more difficult it becomes to bridge the gap through regular savings alone.
What this means for financial advisors and employers
For financial planners, tax professionals and wealth advisors, the findings reflect growing demand for structured retirement advisory rather than product-based investing alone.
The focus increasingly shifts towards:
- inflation-adjusted retirement planning
- healthcare cost estimation
- long-term cash flow modelling
- periodic portfolio review
- tax-efficient retirement structures
Employers may also need to strengthen financial wellness initiatives as retirement readiness becomes a larger workforce concern over time.
Closing perspective
The survey highlights a simple but important reality:
confidence alone does not create retirement security.
As life expectancy rises and long-term costs continue compounding, retirement outcomes will depend less on optimism and more on how early and consistently financial planning begins.
For many individuals, the challenge is no longer whether retirement planning is necessary, but whether enough time remains to build the corpus required for the lifestyle they expect after retirement.