

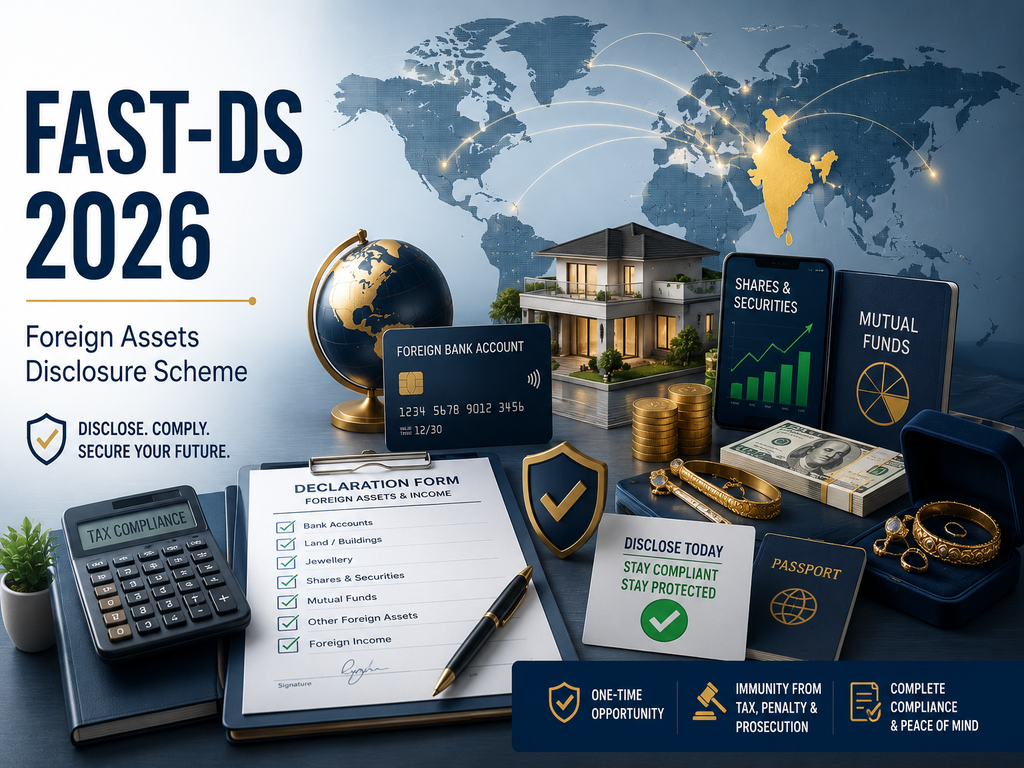
The Government has introduced the Foreign Assets of Small Taxpayers Disclosure Scheme, 2026, known as FAST-DS. It gives eligible taxpayers a one-time chance to disclose certain undisclosed foreign assets and foreign income that were not properly reported earlier, subject to the conditions of the Scheme.
What Assets Can Be Disclosed?
The scheme covers specified undisclosed foreign assets and foreign income, subject to the conditions of the Scheme:
- Bank accounts
- Land or buildings
- Jewellery
- Shares and securities
- Mutual funds
- Artistic works
- Other foreign assets
- Foreign income
Broadly, the scheme works through two categories of cases.
Category 1: Undisclosed Foreign Assets or Income Up to ₹1 Crore
This category applies where the aggregate value of the undisclosed asset located outside India as on 31 March 2026 and the undisclosed foreign income does not exceed ₹1 crore.
The taxpayer needs to pay:
- 30% tax on the relevant undisclosed asset or foreign income; and
- an additional amount equal to 100% of the tax payable.
The total payable effectively comes to 60% of the relevant amount.
Example
Suppose a taxpayer has a foreign bank account worth ₹40 lakh and undisclosed foreign income of ₹30 lakh, totalling ₹70 lakh. Since this is below ₹1 crore, it falls under Category 1.
- Tax on ₹40 lakh = ₹12 lakh
- Tax on ₹30 lakh = ₹9 lakh
- Total tax = ₹21 lakh
- Additional amount equal to 100% of tax = ₹21 lakh
- Total payable = ₹42 lakh
Category 2: Certain Foreign Assets Up to ₹5 Crore
This category offers relief where a foreign asset was not disclosed in the relevant Schedule of the ITR. It applies to an asset that was:
- Acquired from income earned outside India while the assessee was a non-resident, but was not disclosed after the assessee became a resident of India; or
- Acquired from income that had already been offered to tax in India, but was not disclosed in the relevant foreign-assets Schedule of the ITR.
Where the aggregate value of the assets located outside India does not exceed ₹5 crore, the taxpayer can make a declaration by paying a flat fee of ₹1 lakh, subject to the conditions of the Scheme.
Example
Suppose a person bought land abroad while a non-resident and, after becoming a resident of India, failed to disclose it. If the land is valued at ₹4 crore as on 31 March 2026 and all other conditions of the Scheme are satisfied, it may qualify under Category 2, with a fee of ₹1 lakh.
What If There Are Multiple Foreign Assets?
Where a taxpayer holds more than one eligible foreign asset, the aggregate value of the assets needs to be considered for the ₹5 crore limit.
For example:
- Foreign mutual funds = ₹3 crore
- Foreign shares = ₹4 crore
- Total value = ₹7 crore
Since the aggregate value of ₹7 crore exceeds the ₹5 crore limit, the taxpayer would not qualify for Category 2.
Who Is the “Assessee” Eligible to Declare Under the Scheme?
An assessee eligible under the Scheme is one who is resident in India, as per section 6 of the Income-tax Act, 1961, in the relevant previous year, or is a non-resident or resident but not ordinarily resident (RNOR) under section 6(6) of that Act, but was resident in India either in the year to which the undisclosed foreign income under section 4 of the Black Money Act, 2015 relates, or in the year in which the undisclosed foreign asset was acquired.
What Is the Benefit of This Scheme?
Once a valid declaration is made and the required payment is made, the taxpayer can get immunity, subject to the Scheme’s conditions, from:
- Further tax
- Penalty
- Prosecution
under the Black Money (Undisclosed Foreign Income and Assets) and Imposition of Tax Act, 2015, in respect of the income or asset declared.
The income or amount of investment in the asset declared under the Scheme is also not included in the total income of the taxpayer under the Income-tax Act, 1961 or the Black Money Act, 2015, subject to the applicable provisions.
What Is the Valuation Date?
The valuation date for the Scheme is 31 March 2026. The fair market value of the foreign asset is generally determined as the higher of the cost of acquisition and the price the asset would ordinarily fetch in the open market on the valuation date, subject to the detailed valuation rules.
Where the prescribed market valuation is not carried out, the indexed cost of acquisition is deemed to be the fair market value.
Taxpayers should maintain appropriate valuation evidence and, where applicable, a valuation report from a recognised valuer in the country where the asset is located.
What Is the Time Limit to Make the Declaration?
- Scheme starts: 16 August 2026
- Last date to declare: 31 December 2026
- Mode: Electronically through Form 1
What Happens After Filing Form 1?
After electronic verification of Form 1, the income-tax authority communicates the amount payable through Form 2.
The amount generally has to be paid within two months from the end of the month in which the order is received. If the taxpayer is unable to pay within this period, a further period of up to two months is available, subject to simple interest of 1% for every month or part of a month of delay.
The payment is then reported electronically through Form 3, along with proof of payment. Once the payment is confirmed, the income-tax authority issues Form 4 certifying the payment.
Conclusion
FAST-DS 2026 gives eligible taxpayers a one-time opportunity to disclose certain undisclosed foreign assets and income and bring them into compliance with the law, with the tax or fee depending on which category applies.
Taxpayers should carefully check their eligibility, determine the value of their foreign assets as on 31 March 2026 in accordance with the prescribed valuation rules, and work out the applicable tax or fee before filing.
The declaration window is open from 16 August 2026 to 31 December 2026.
For those who qualify, FAST-DS can be a useful opportunity to regularise previously undisclosed foreign assets and obtain immunity from further tax, penalty and prosecution, subject to fulfilment of all conditions of the Scheme.